WHY PROPERTIES ARE RETHINKING LAUNDRY ENTIRELY
Nobody decided to own a laundry business. It came with the building.
A QUIET CONVERSATION IS STARTING
Nothing broke. Nobody issued a mandate. There is just a real alternative now. Laundry has been inside residential buildings for decades and was never really questioned. Machines went in, residents used them, ownership handled the replacement cycle when it came up. It was infrastructure, and nobody thought of it as a category worth reconsidering.
A growing number of properties are now asking whether the way they have always handled laundry is still the right approach. What is notable is that these conversations are not coming from one direction. Some start with an operations question. Some start with a capital decision. Some start because a resident survey put laundry near the top of the friction list. The entry point varies, but the conversation tends to end up in the same place.
Laundry is being evaluated as part of resident experience, not just as equipment.
THE FIRST QUESTION PROPERTIES ASK
Is what we are doing with laundry actually the best approach for this building?
That question rarely arrives with a plan behind it. It surfaces at a predictable moment, when someone is about to commit to laundry infrastructure and wants to know what else exists first.
THE MOMENT TENDS TO BE ONE OF THESE
- An equipment replacement cycle is approaching and the capital question opens the conversation
- A renovation is underway and laundry rooms are being reconsidered as part of the broader plan
- Resident feedback has flagged laundry as a recurring friction point
- An operational review surfaces laundry as a system that takes more managing than it should
None of these start with urgency. They start with curiosity. An asset manager looking at the capital picture, or an operations leader tired of the maintenance cycle, wants to understand the options before making another long-term commitment.
Nobody is looking for a new laundry vendor. They are looking for a different answer.
PATTERN ONE: OPERATIONAL SIMPLICITY
The first point of interest is almost always operational, not financial. It is not resident experience either. Operations comes up first, consistently, and it does not need to.
THE PATTERN IS FAMILIAR TO ANYONE WHO MANAGES BUILDINGS
Equipment eventually fails, and when it does, someone has to coordinate the response
Repairs require vendor scheduling, follow-up, and resident communication
Laundry rooms require ongoing oversight, cleanliness, availability, access
Residents report availability issues, and those reports land with the property team
The maintenance cycle repeats, reliably, throughout the life of the equipment
None of these are catastrophic on their own. Laundry is rarely the largest operational burden in a building. It is a consistent one, and consistency is what makes it worth noticing. What operators tend to observe is that removing equipment does not just solve a maintenance problem. It removes a category of recurring responsibility from the team’s plate entirely. For anyone managing day-to-day operations across a portfolio, removing the category is worth more than removing the individual tasks.
PATTERN TWO: RESIDENT EXPERIENCE
Almost every resident uses laundry, which is why small changes to it get noticed. Once the operational question opens up, resident experience surfaces quickly. Laundry is one of the few building services nearly every resident interacts with on a regular basis, so even small changes in how it works are noticeable.
TRADITIONAL RESIDENT FRICTION
The friction residents have historically worked around is not dramatic.
- Trips to a shared laundry room
- Waiting for a machine to free up
- Timing a schedule around equipment availability
INDUSTRY SHIFT
These are not complaints people raise in renewal conversations. They are part of the texture of living in the building, and that texture accumulates.
What is driving the shift is not dissatisfaction with laundry specifically. It is a broader pattern. Across almost every area of daily life, residents have moved toward convenience-based models: on-demand services, same-day everything. Laundry stayed largely unchanged while everything around it evolved. Operators who notice this gap start asking a simple question. If the rest of the resident experience is moving toward convenience, why is laundry still organized around machine availability?
Increasingly, the answer is that it does not have to be.
PATTERN THREE: FINANCIAL STRUCTURE
The money question arrives last, and it is where the picture gets interesting. Once properties have worked through the operational and resident dimensions, the economics enter the conversation. That is where it becomes most interesting for ownership and asset management.
COSTS THAT ARE EASY TO OVERLOOK
They are spread across the life of the equipment, which is what makes them easy to miss.
- Replacement cycles come around every several years
- Maintenance accumulates in between
- Utilities run continuously
- Oversight is not free
No single line is large. Added together across the lifecycle of a property, the cost of running laundry as equipment is higher than it appears.
WHAT CHANGES UNDER A SERVICE MODEL
- The equipment cost shifts
- The maintenance responsibility moves
- Depending on how the service is positioned, it can create a new line in the asset’s financial picture rather than simply replacing a cost
For asset management, this is not just an operational change. It is a reclassification of where laundry sits in the building’s economics, and that affects NOI, capital planning, and how the property is positioned in its submarket.
PATTERN FOUR: ALMOST NOBODY STARTS PORTFOLIO-WIDE
The evaluation stays small first, and it stays small on purpose.
Very few ownership groups, whatever the portfolio size, deploy a fundamentally different operational model across every building at once. The risk profile does not support it, and the information is not there yet. A model that performs well in a pitch is different from a model that performs well in a building with real residents and a real operations team.
WHAT HAPPENS INSTEAD, ALMOST EVERY TIME
- One property runs the model in real operating conditions
- The team watches how it performs, how it integrates, what they actually have to manage, and what breaks
- Residents experience the service directly, and their feedback enters the conversation
- If the performance holds, portfolio consideration follows because of the evidence
Package management systems entered multifamily this way. So did building-wide internet, and smart access when it replaced key fobs in competitive buildings.
The industry does not move all at once. It moves building by building.
WHAT IS ACTUALLY EMERGING
A new category, not a new vendor.
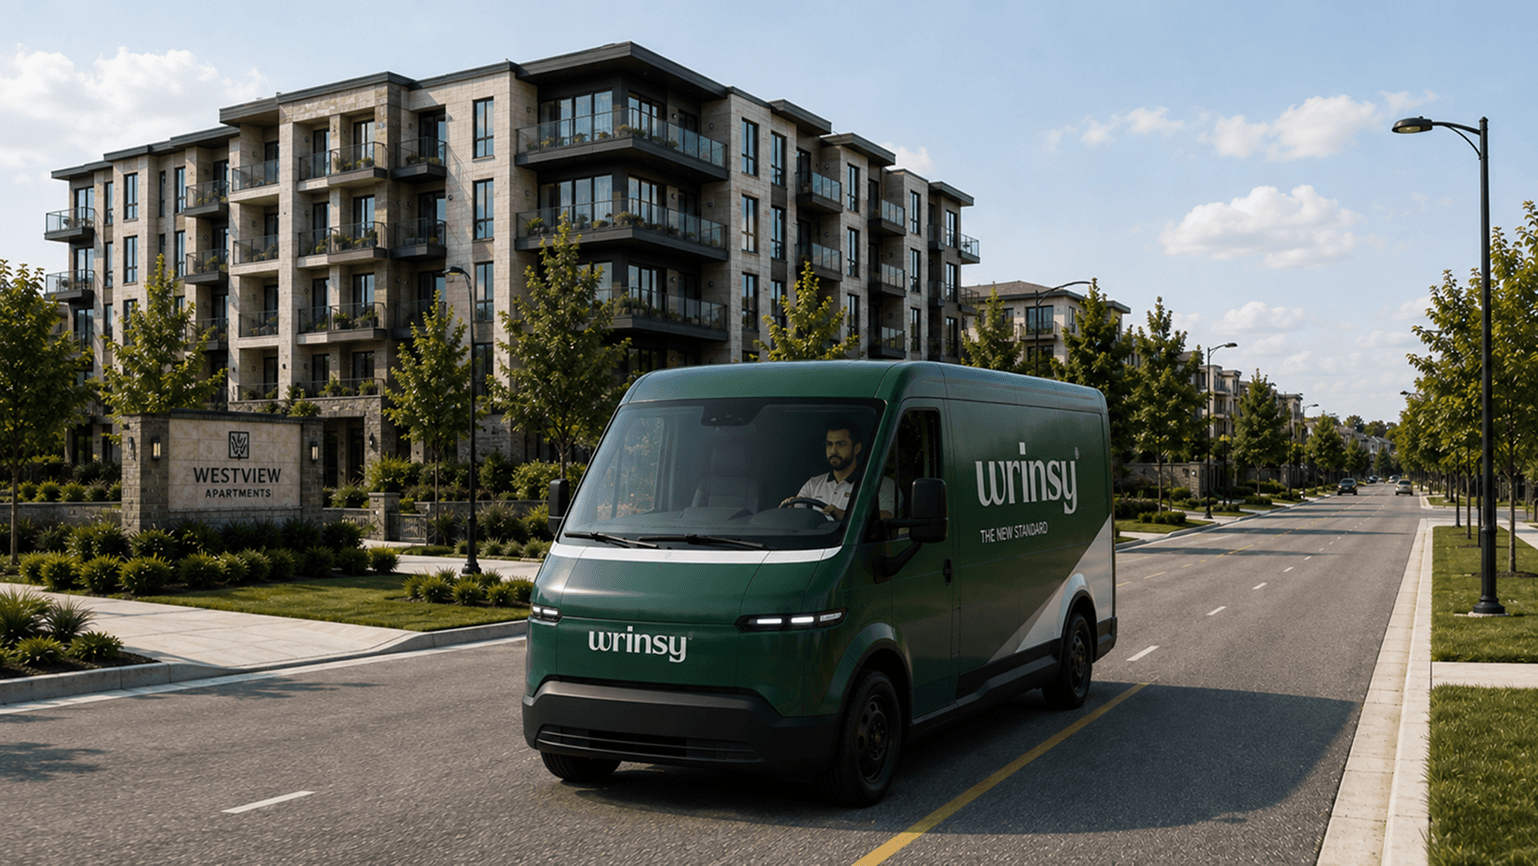
The need has not changed. The way of meeting it has.
Residents will always need clean clothes. That part is stable. What is shifting is whether laundry has to be delivered through equipment inside the building, or whether it can be delivered as a managed service that operates outside the building's infrastructure entirely. A small but growing number of properties are evaluating exactly that. They are not looking to upgrade their laundry rooms. They are asking whether the laundry room model still makes sense.
WRINSY
wrinsy replaces on-site laundry equipment with a fully managed pickup and delivery service built for multifamily. Residents put their laundry in the secure wrinsy box outside their door. wrinsy handles everything from there: pickup, cleaning, and next-day return. The property stays informed without doing any of the work.
No equipment to manage, no vendors to coordinate, and no resident complaints about machine availability. The operational complexity moves outside the building. For most properties exploring this category for the first time, the most useful thing is not a pitch. It is seeing the patterns clearly. Once the operational picture, the resident experience question, and the financial structure are all visible at once, the decision tends to become more straightforward than it first appeared.
The patterns, once visible, tend to make the path obvious.
Related Resources
View allWHO IS WRINSY
Laundry infrastructure replaced with a fully managed service.
HOW WRINSY WORKS
A structured pickup and return service your staff never has to manage.
FINANCIAL IMPACT
What wrinsy does to NOI, CapEx, and reclaimed space, in plain numbers.